

Dollarwise: Budget & Tracking
3.3

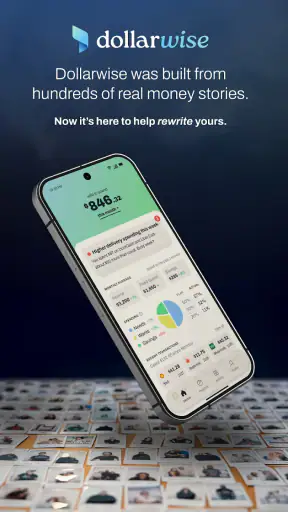
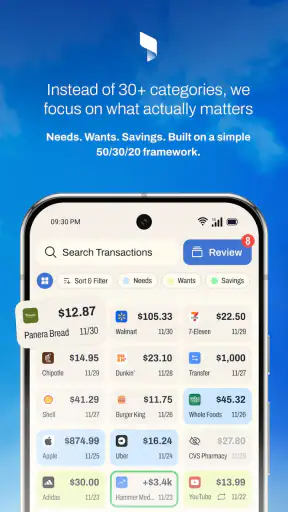
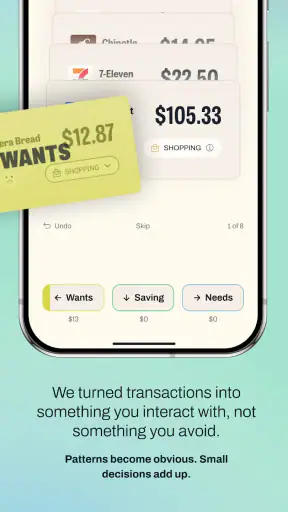
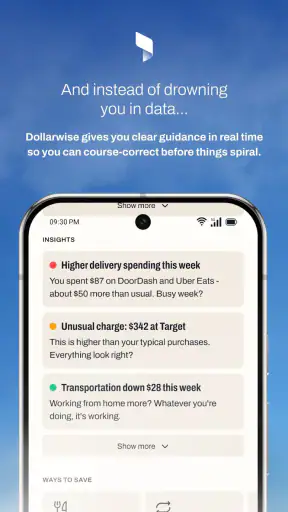
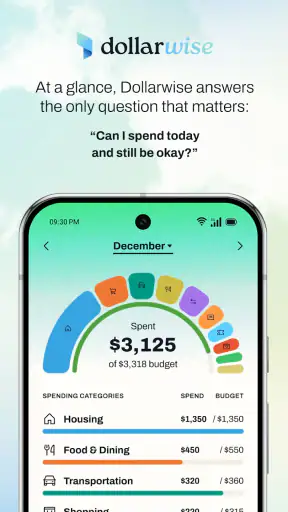
I spent time with Dollarwise: Budget & Tracking as a personal finance app, and the part that matters most is its focus on turning everyday spending into a story you can actually understand. That sounds simple, but it changes how I approached my money. Instead of treating a budget as a one-time setup, I used the app as a place to notice patterns, check progress, and decide what needed attention before the month got away from me.
That central idea makes Dollarwise more approachable than a finance tool built around dense reports. It is free to download, aimed at everyone, and developed by HammerMedia. The app has built a modest audience, with more than one hundred thousand installs, while its average score sits at 3.3 from roughly two thousand ratings. Those figures suggest a useful but uneven experience: enough people find value in it, yet it is not the kind of app I would recommend blindly to every type of budgeter.
Turning spending into a usable money story
The strongest capability here is the combination of budgeting and expense tracking. I found the distinction important. A list of transactions tells me what already happened; a budget gives those transactions meaning. When both are viewed together, I can ask a more useful question than “Where did my money go?” I can ask whether my current habits are supporting the plan I made at the start of the month.
That is the practical value of the app’s “rewrite your money story” approach. It is less about making a dramatic financial transformation in one sitting and more about changing the conversation I have with my own spending. A restaurant purchase is no longer just an isolated charge. In the context of a budget, it becomes part of a pattern that may be comfortable, too high, or perfectly reasonable depending on the rest of the month.
I especially liked this perspective for people who feel intimidated by personal finance software. Many alternatives lead with investment dashboards, account connections, credit information, or elaborate forecasting. Those tools can be powerful, but they also create a lot of visual and mental noise. Dollarwise is more suitable for someone whose first goal is simply to understand regular spending and create a routine around it.
That simplicity has a limit, though. If you want a full financial command center, this is unlikely to replace a more advanced service. I would not choose it solely because it sounds easier. I would choose it because the basic act of recording and reviewing spending is the part I most need help maintaining.
Why the tracking habit matters more than the first budget
In my experience, the first budget is rarely the difficult part. The real test comes several days later, when purchases are no longer fresh in my mind and the categories begin to reflect real life rather than good intentions. Dollarwise is most useful when I return regularly, because the tracking process gives the budget a chance to become accurate instead of remaining a hopeful estimate.
That creates an important trade-off. A finance app cannot make a budget honest if I avoid entering purchases or fail to review them. The app can provide structure, but it cannot remove the small responsibility of keeping that structure current. For someone willing to build a short checking routine, that is manageable. For someone looking for completely automatic financial management, the experience may feel too hands-on.
I recommend treating the app as a quick financial check-in rather than a place to stare at constantly. A brief review after ordinary spending helps prevent small purchases from becoming invisible. A longer review at the end of the week is useful for spotting categories that are drifting. This two-step approach is more realistic than trying to perform a perfect budget review only once a month.
How I used it during an ordinary week
My most useful test was a normal week rather than an unusually expensive one. I imagined receiving income, paying recurring bills, buying groceries, ordering food once, and making a few low-cost purchases that would be easy to forget. The important question was not whether Dollarwise could make the week look tidy. It was whether the app could help me see the difference between planned spending and accidental spending.
I began with the categories that mattered to my routine instead of trying to classify every possible expense. That is a worthwhile approach with this app because too much detail can make tracking feel like clerical work. Once the main areas were clear, I could use the record of spending to judge whether a category was genuinely expensive or simply had one unusual purchase in it.
For example, a grocery run near the start of the week may look harmless on its own. Add a second trip, a convenience purchase, and a takeaway meal, and the total tells a different story. The useful insight is not that any one purchase was automatically wrong. It is that the combined effect can quietly reduce the room available for later needs. Dollarwise works best when I use the record to make an adjustment early, rather than as a tool for criticizing myself afterward.
One practical workflow is to review the app before making a discretionary purchase, not after. If I am considering an unplanned expense, checking the relevant budget first gives me context. I can decide whether the purchase fits, whether another category needs to be restrained, or whether the expense should wait. That small pause is one of the app’s more meaningful benefits because it turns tracking into a decision tool.
Another useful habit is separating fixed obligations from flexible spending in my own review. A budget can appear healthy when recurring bills have not yet arrived, or look alarming when several obligations land close together. Looking at the timing of expenses helps avoid reacting to a misleading snapshot. Dollarwise does not need to make the decision for me; its value is giving me a clearer record to work from.
A realistic use case: the middle of the month
Imagine someone who starts the month with a reasonable plan, then reaches the middle of the month wondering why the remaining balance feels smaller than expected. This is where I think the app has its clearest everyday role. Instead of relying on memory, that person can review tracked spending and identify whether the pressure came from food, transport, shopping, or several small categories working together.
The next step is not necessarily cutting everything. It may be choosing one category to watch for the rest of the month. That is a more sustainable response than creating an extreme restriction that will be abandoned after a few days. I found the app more helpful for this kind of course correction than for grand financial planning.
There is also a useful emotional benefit. When spending is vague, it is easy to feel that money is disappearing randomly. A categorized record replaces that vague worry with something more specific. Even if the result is not pleasant, specificity makes action easier. I can change a behavior I can name; “I am bad with money” is much less useful than “small food purchases are taking more room than I expected.”
Where Dollarwise fits beside other finance apps
Compared with a spreadsheet, Dollarwise offers a more focused experience for people who do not want to design their own formulas, tabs, and visual summaries. A spreadsheet remains better for someone who enjoys total control or needs unusual calculations. I would choose the spreadsheet route for a household with complicated shared finances, irregular business costs, or a strong preference for customizing every detail.
Compared with a banking app, Dollarwise has a different purpose. A bank app is the authoritative place to check account balances and completed transactions. It is usually not designed to help me think through a personal spending plan in a calm, deliberate way. I would still use my bank for verification, while using Dollarwise for the budgeting habit and the broader interpretation of spending.
Compared with a feature-heavy personal finance platform, Dollarwise is easier to understand if the main need is budgeting rather than a complete financial overview. The alternative may be better for users who want investments, credit monitoring, broad account aggregation, or detailed financial projections in one place. The advantage of Dollarwise is that it keeps the central task narrower, which can make it less intimidating for a beginner.
That narrow focus also means I would not treat it as a substitute for financial advice. It can organize personal spending, but it does not turn a difficult financial situation into an easy one. If someone is dealing with debt decisions, tax questions, or complex household obligations, the app may be a helpful record-keeping companion, not the complete answer.
The friction I noticed before recommending it
The biggest limitation is the need for consistency. Any manual or semi-manual tracking routine can become frustrating when I fall behind. Once several days of purchases accumulate, reconstructing them is less pleasant and the budget becomes less trustworthy. My advice is to start with a small number of meaningful categories and establish a repeatable review time before attempting a highly detailed system.
There is also a financial consideration beyond the free entry point. Dollarwise is free to use, but it includes optional in-app purchases ranging from about fifteen dollars to five hundred dollars per item. That is a very broad range, so I would pay close attention to each purchase screen and avoid assuming that every useful function is included without additional cost. Anyone installing it should be comfortable checking what is free and what requires payment before committing to an upgrade.
The average rating is another reason I would approach it with realistic expectations. A score of 3.3 indicates that the experience has not been equally smooth for everyone. I would not interpret that as proof that the app is unsuitable, but I would install it with a short trial mindset: see whether the tracking flow feels natural, whether the organization matches my habits, and whether I can maintain it for a week before building my entire budget around it.
The app is available for Android devices running version 7.0 or later, which covers many older phones. That is convenient for people who do not upgrade frequently. Still, compatibility alone does not guarantee that the app will fit every personal workflow. A person who needs advanced automation or a very specific reporting format should compare the experience against a more specialized option before moving all financial records into it.
Who gets the most from this approach
I think Dollarwise is best for a beginner who wants a clear starting point, a person trying to stop losing track of small purchases, or anyone who has tried budgeting in theory but never created a regular review habit. It can also suit someone who prefers a dedicated finance app over keeping sensitive money notes in a general-purpose document or spreadsheet.
The app is particularly useful when the goal is behavioral awareness. If I want to discover why a month feels expensive, test a realistic spending limit, or create a pause before optional purchases, the budgeting-and-tracking combination gives me a practical framework. The benefit comes from repeated use, not from opening it once and expecting an instant diagnosis.
I would be more cautious recommending it to a couple who needs shared, synchronized planning, a freelancer managing business and personal money separately, or an experienced budgeter who already has a detailed system. Those users may find the app too limited or too dependent on their own manual organization. A spreadsheet or broader finance platform could be the better choice when flexibility and depth matter more than approachability.
It is also not the right match for someone who dislikes entering or reviewing financial information. No friendly interface can solve that mismatch. In that situation, a service centered on automatic account connections may be more convenient, provided the user is comfortable with that approach. Dollarwise makes more sense for people who want to stay consciously involved in the process.
My recommendation after using it
My recommendation is measured but positive. Dollarwise: Budget & Tracking is not a complete financial command center, and I would not buy into it expecting one. Its real strength is more focused: it encourages me to connect individual spending decisions with a budget I can review and adjust. That is valuable precisely because it addresses a common everyday problem rather than trying to cover every financial topic.
Before relying on it, I would spend the first week testing the routine. Add the expenses that genuinely shape the month, review the categories at a fixed time, and see whether the app helps me make decisions before money becomes tight. I would also inspect any paid options carefully, especially given the wide range of in-app purchase amounts.
HammerMedia’s app has enough reach to be worth considering, but its middling average score tells me to judge it by personal fit rather than popularity alone. For a beginner who wants a straightforward way to understand spending, it may become a useful daily or weekly checkpoint. For users demanding automation, complex household planning, or advanced financial analysis, a different tool will probably serve them better.
In the end, I see Dollarwise as a habit-building companion. Its most important effect is not showing me a number; it is encouraging me to notice the choices behind that number while there is still time to change course. If that is the part of budgeting I struggle with, the free app is worth trying. If I already have a reliable system or need much deeper financial management, I would skip it and choose a more specialized alternative.
3.3
1.16K Reviews
Pros
- Simple interface makes daily expense tracking quick and approachable.
- Custom categories help organize spending around personal habits.
- Budget progress gives a clear view of remaining funds.
- Recurring transactions reduce the effort of logging regular bills.
- Useful spending insights can reveal patterns over time.
Cons
- Some advanced features may require a paid subscription.
- Manual entry can become tedious for users with many transactions.
- Limited bank integration may reduce automatic tracking convenience.
- Detailed reports could feel basic for users needing financial analysis.
- Privacy-conscious users may want more clarity about data handling.


